
Continuous double auction (zero-intelligence order book)#
Field: economics · Zoo name: order_book · Module: modelly.zoo.order_book.model
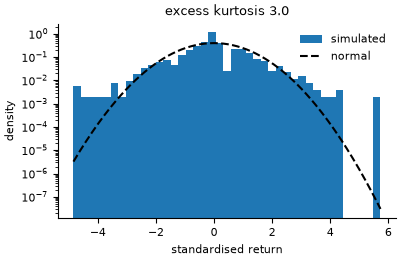
A limit order book on an integer price grid, fed by random order flow, as in the
zero-intelligence model of Farmer, Patelli and Zovko. With probabilities in proportion to
their rates, an event is a market buy or sell, which takes one unit at the best opposite
price; a limit buy or sell, which rests at a price drawn uniformly 1 .. window ticks
inside the opposite best quote, so it never crosses; or the cancellation of a uniformly
random resting order. No trader has a strategy, yet the prices show some of the stylised
facts of real markets.
How it is written#
The book is two numpy arrays of depth per tick, bids and asks; the best quotes are the
last and first non-empty levels. Each event draws its kind from the six rates
(model.rates()), and a cancellation picks its order in proportion to depth with one
cumsum and searchsorted. An event that would empty a side becomes a limit order on that
side. A step is events events; the mid price and the spread are collected after each step.
from modelly.zoo.order_book.model import OrderBook, OrderBookScenario

model = OrderBook(OrderBookScenario(rng=42))
model.run()
model.best_bid(), model.best_ask()
model.returns()  # log returns of the mid price, step to step
model.datacollector.get_model_vars_dataframe()  # mid price and spread per step
Parameter |
Default |
Meaning |
|---|---|---|
|
|
number of price levels |
|
|
limit orders rest |
|
|
rate of market orders, both sides together |
|
|
rate of limit orders, both sides together |
|
|
rate of cancellation per resting order |
|
|
orders per level in the |
|
|
order events per step |
|
|
run length of |
Validation#
Real returns have fat tails: their excess kurtosis is positive (Cont, 2001).
tests/zoo/test_order_book.py runs 2,000 steps with three seeds and checks the excess
kurtosis of the mid-price returns is above five times sqrt(24 / n), its standard error if
the returns were normal; it is about thirty standard errors in practice. It also checks the
spread is always at least one tick, that aggressive market orders never empty a side of a
one-order book, and that the same seed gives the same price path.
References#
Farmer, J. D., Patelli, P. and Zovko, I. I. (2005). The predictive power of zero intelligence in financial markets. PNAS, 102(6), 2254-2259.
Cont, R. (2001). Empirical properties of asset returns: stylized facts and statistical issues. Quantitative Finance, 1, 223-236.
Start a project from it with modelly zoo copy order_book my_market.